Wholesale Diamond
Market Report
Wholesale price index, supply chain movements, and trade desk observations from our Mumbai office — updated monthly by the Anand Exports procurement team.
June 2026: Cautious Stability at the Top End.
The wholesale natural diamond market enters June 2026 in a state of cautious stability. D–H / FL–VS2 goods in the 1–3ct range continue to command firm premiums driven by persistent demand from the Middle East (UAE, KSA), Hong Kong, and private Swiss allocators. Below 0.80ct commercial quality is experiencing modest pressure as US bridal volume has not recovered to 2022 levels.
Rough supply remains constrained. De Beers Sight allocations in May were reduced 8% versus Q1 averages, and ALROSA's secondary-market presence remains structurally limited. This rough tightness is supporting polished 1ct+ prices and is expected to persist through Q3 2026.
Our desk is seeing increased requests for "natural provenance documentation" from European buyers — a direct consequence of the EU CSDDD rollout.
Indicative wholesale prices. Actual prices depend on specific stone characteristics, certification, and order volume. Contact us for firm quotes.
Supply, Demand & Trade
Corridor Updates.
De Beers Sight Allocations Reduced
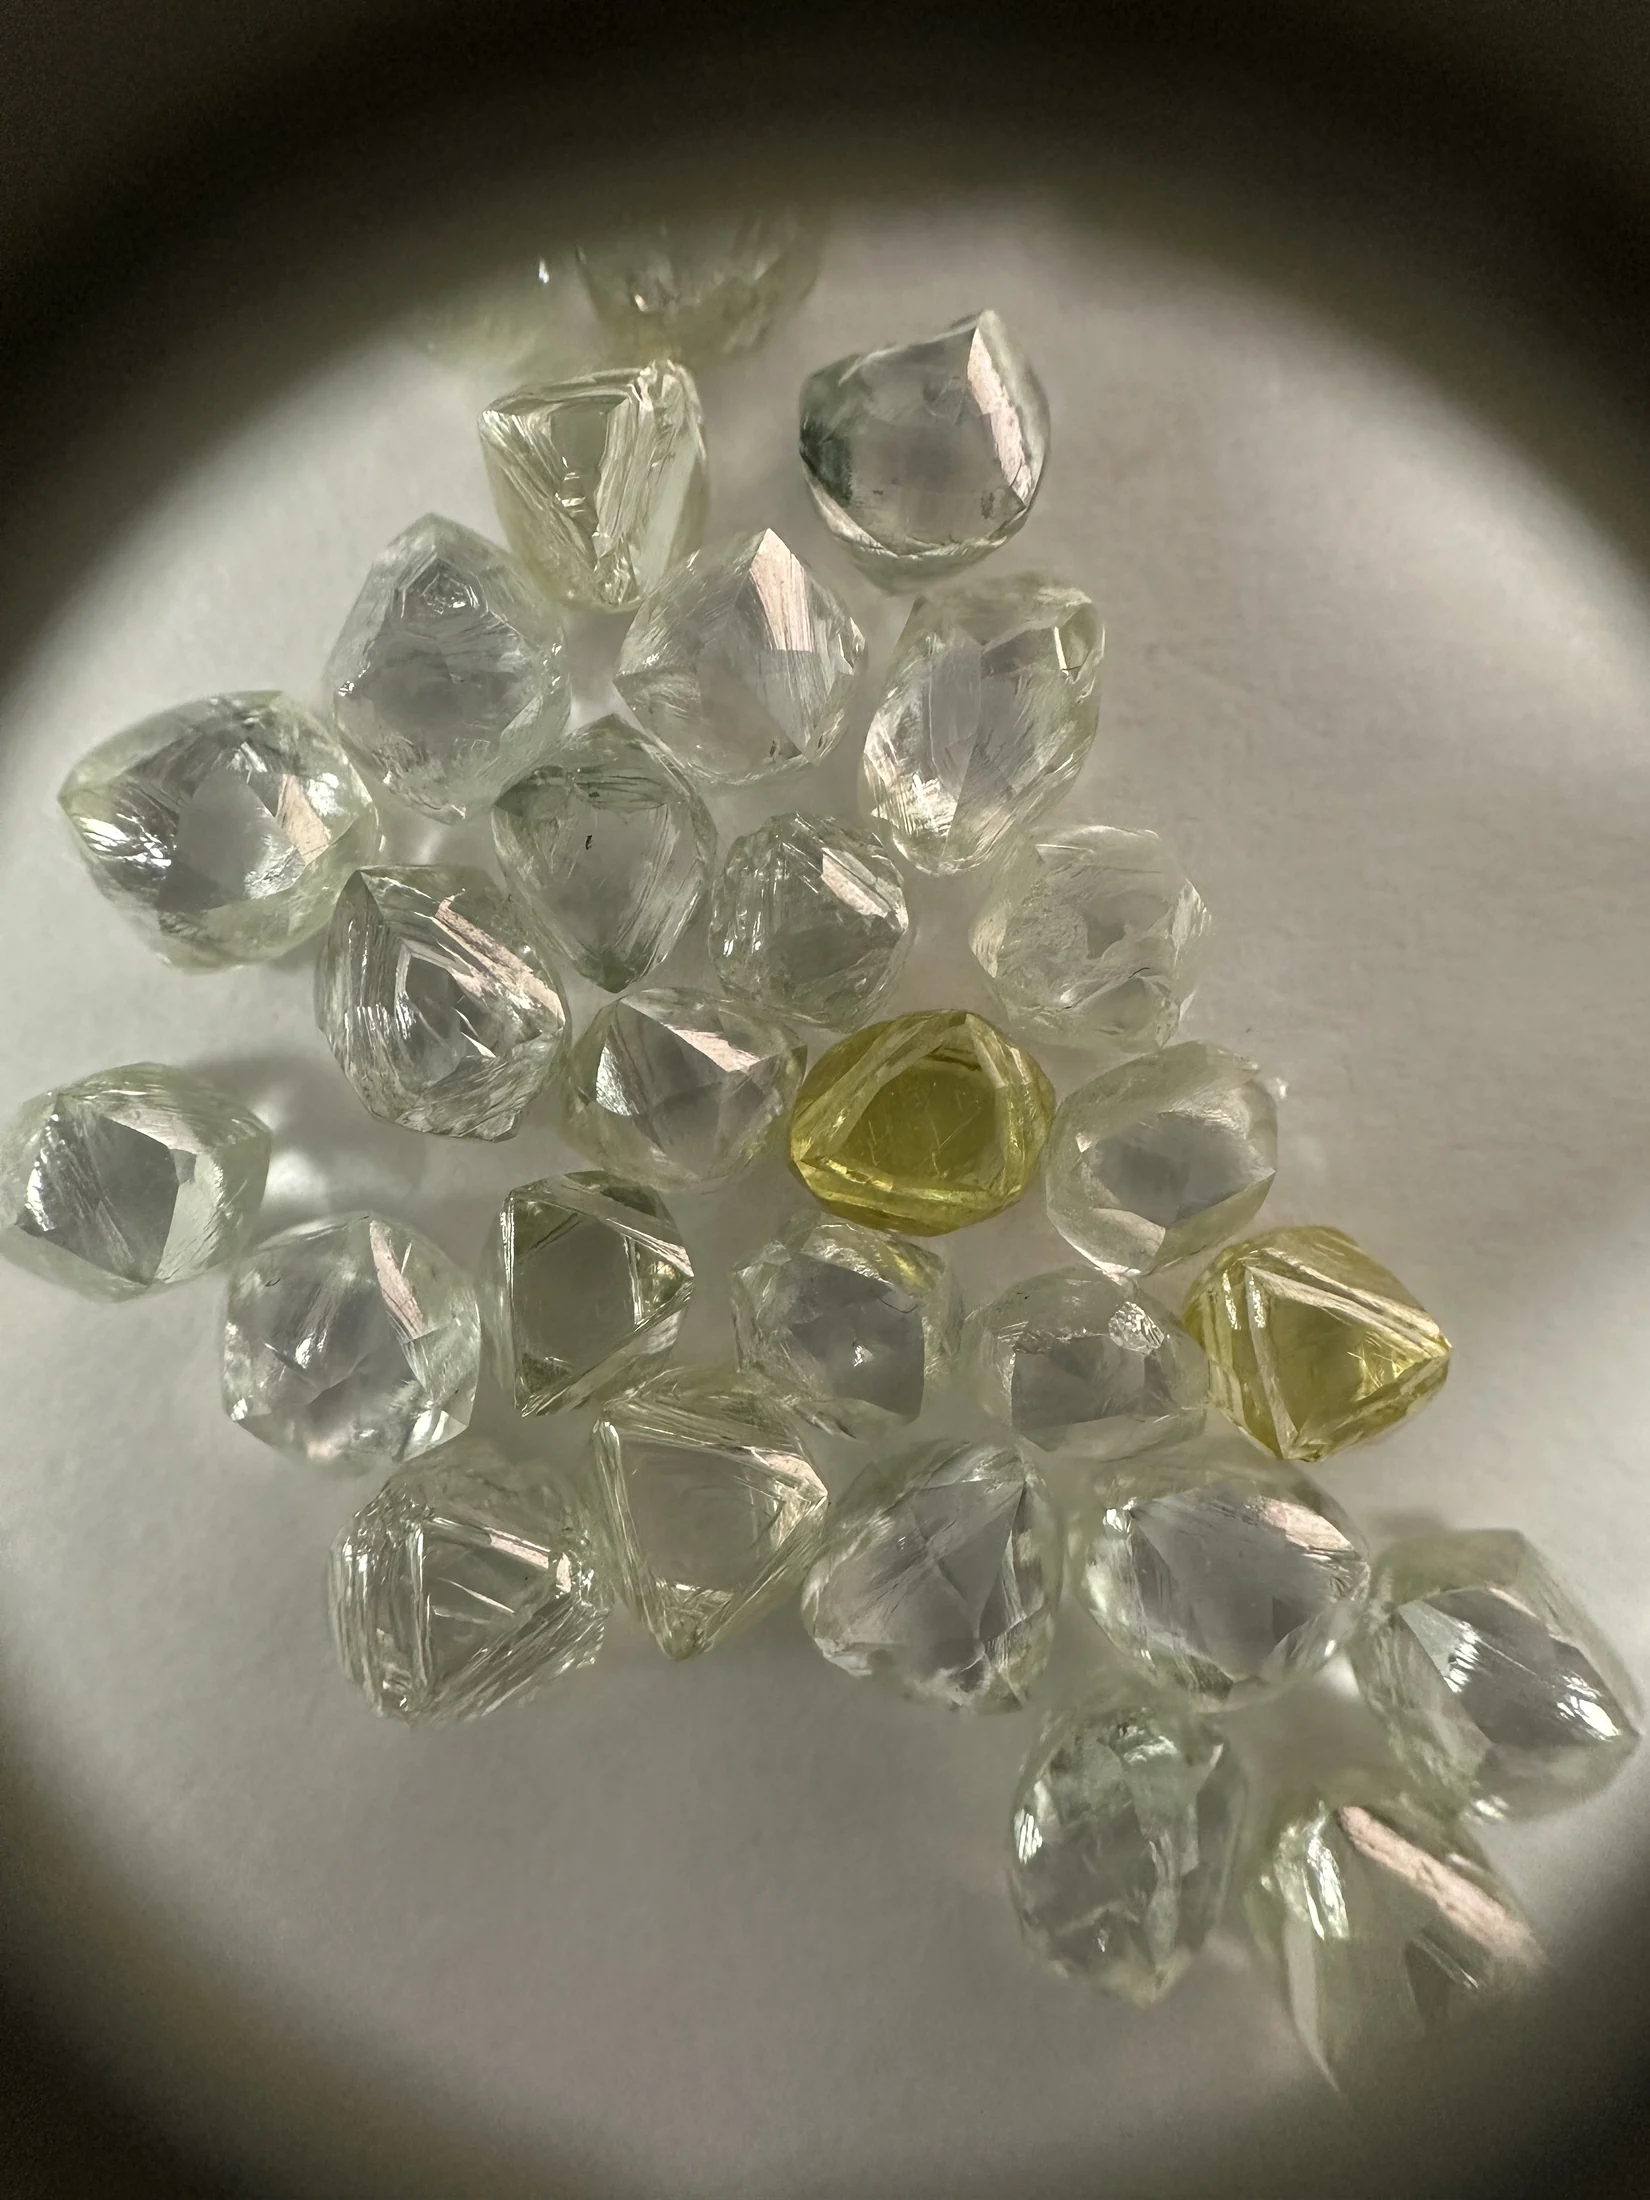
The May 2026 Sight saw allocations trimmed 8% on the previous quarter, primarily in commercial round sizes (0.30–0.80ct). De Beers cited slowing retail recovery in the US as justification. Smaller Sight offerings are expected to support polished prices in H2 2026. Botswana Diamonds/HB Antwerp parcels remain well-bid in the Belgium corridor.
Secondary Market Volumes Constrained
ALROSA rough continues to flow through Indian intermediaries at a premium to pre-2022 levels. The compliance burden is real — buyers must now self-certify Russia-origin goods under EU sanctions requirements. Volumes reaching our desk are approximately 40% of 2021 levels, which is creating measurable scarcity in the 0.50–1.20ct octahedral range.
UAE & KSA: Strong Bridal Demand
Dubai and Riyadh continue to drive demand for 1–3ct D–H / VVS-VS certified round brilliants. DIFC jewellers are seeing record footfall from regional ultra-HNW buyers upgrading heirloom collections. We have seen a 22% increase in UAE-destination export requests year-to-date, particularly for triple excellent cut rounds with no fluorescence.
Hong Kong Recovery; Japan Stable
Hong Kong jewellery retail has recovered to approximately 85% of 2019 volumes following the stabilisation of cross-border travel. Demand is concentrated in 0.80–2.00ct fancy shapes — oval and pear continue to outperform. Japan remains a consistent market for matched melee parcels and H–J colour goods for local manufacture.
Factory Utilisation at 78%
Surat manufacturing capacity utilisation sits at approximately 78% across the industry, up from 70% in Q4 2025. Our facility is operating at full capacity with a 6-week polishing queue for custom orders. Labour costs have increased ~6% YoY following state minimum wage revision, partially offset by efficiency gains from upgraded laser planning technology.
What We'd Buy
This Month.
Based on current supply dynamics and buyer demand signals, our procurement desk highlights the following opportunities for June 2026:
1.00–1.20ct F–G / VVS2–VS1, EX cut, no fluorescence
Tightest supply-demand dynamic of any category. UAE and Japan demand is outstripping available certified parcels. Price expected to hold or strengthen through Q3. Strong buy for inventory.
Oval cut, 1.50–2.50ct, H–I / VS1–VS2
Oval demand from Hong Kong and European fashion jewellery has driven premiums 8–12% above equivalent rounds in the same quality. Supply of well-cut large ovals remains constrained — sourcing early-quarter is recommended.
Matched melee, 0.18–0.22ct, G–H / VS–SI1
Resurgent demand from Japanese and Korean gold jewellery manufacturers. Retail buyers increasingly want "natural stone" certification for branded pieces.
Wholesale Diamond Pricing — FAQ
What is the current wholesale price per carat for a 1ct G/VS1 round brilliant?
As of June 2026, a 1ct G/VS1 Excellent cut GIA-certified round brilliant trades at approximately $4,800–$5,600/ct at the wholesale level, depending on fluorescence, vendor, and lot size. Prices are benchmarked against the Rapaport Price List with typical trader discounts of 15–25% off Rap.
Are natural diamond prices rising or falling in 2026?
Natural diamond wholesale prices have seen modest softening in the 0.30–0.70ct commercial quality range due to reduced US retail volume, but 1ct+ D–J / VVS-VS goods remain stable. High-jewellery demand from the Middle East and China continues to support the top end. The overall market is cautiously stable rather than declining.
What is the average price per carat for wholesale rough diamonds?
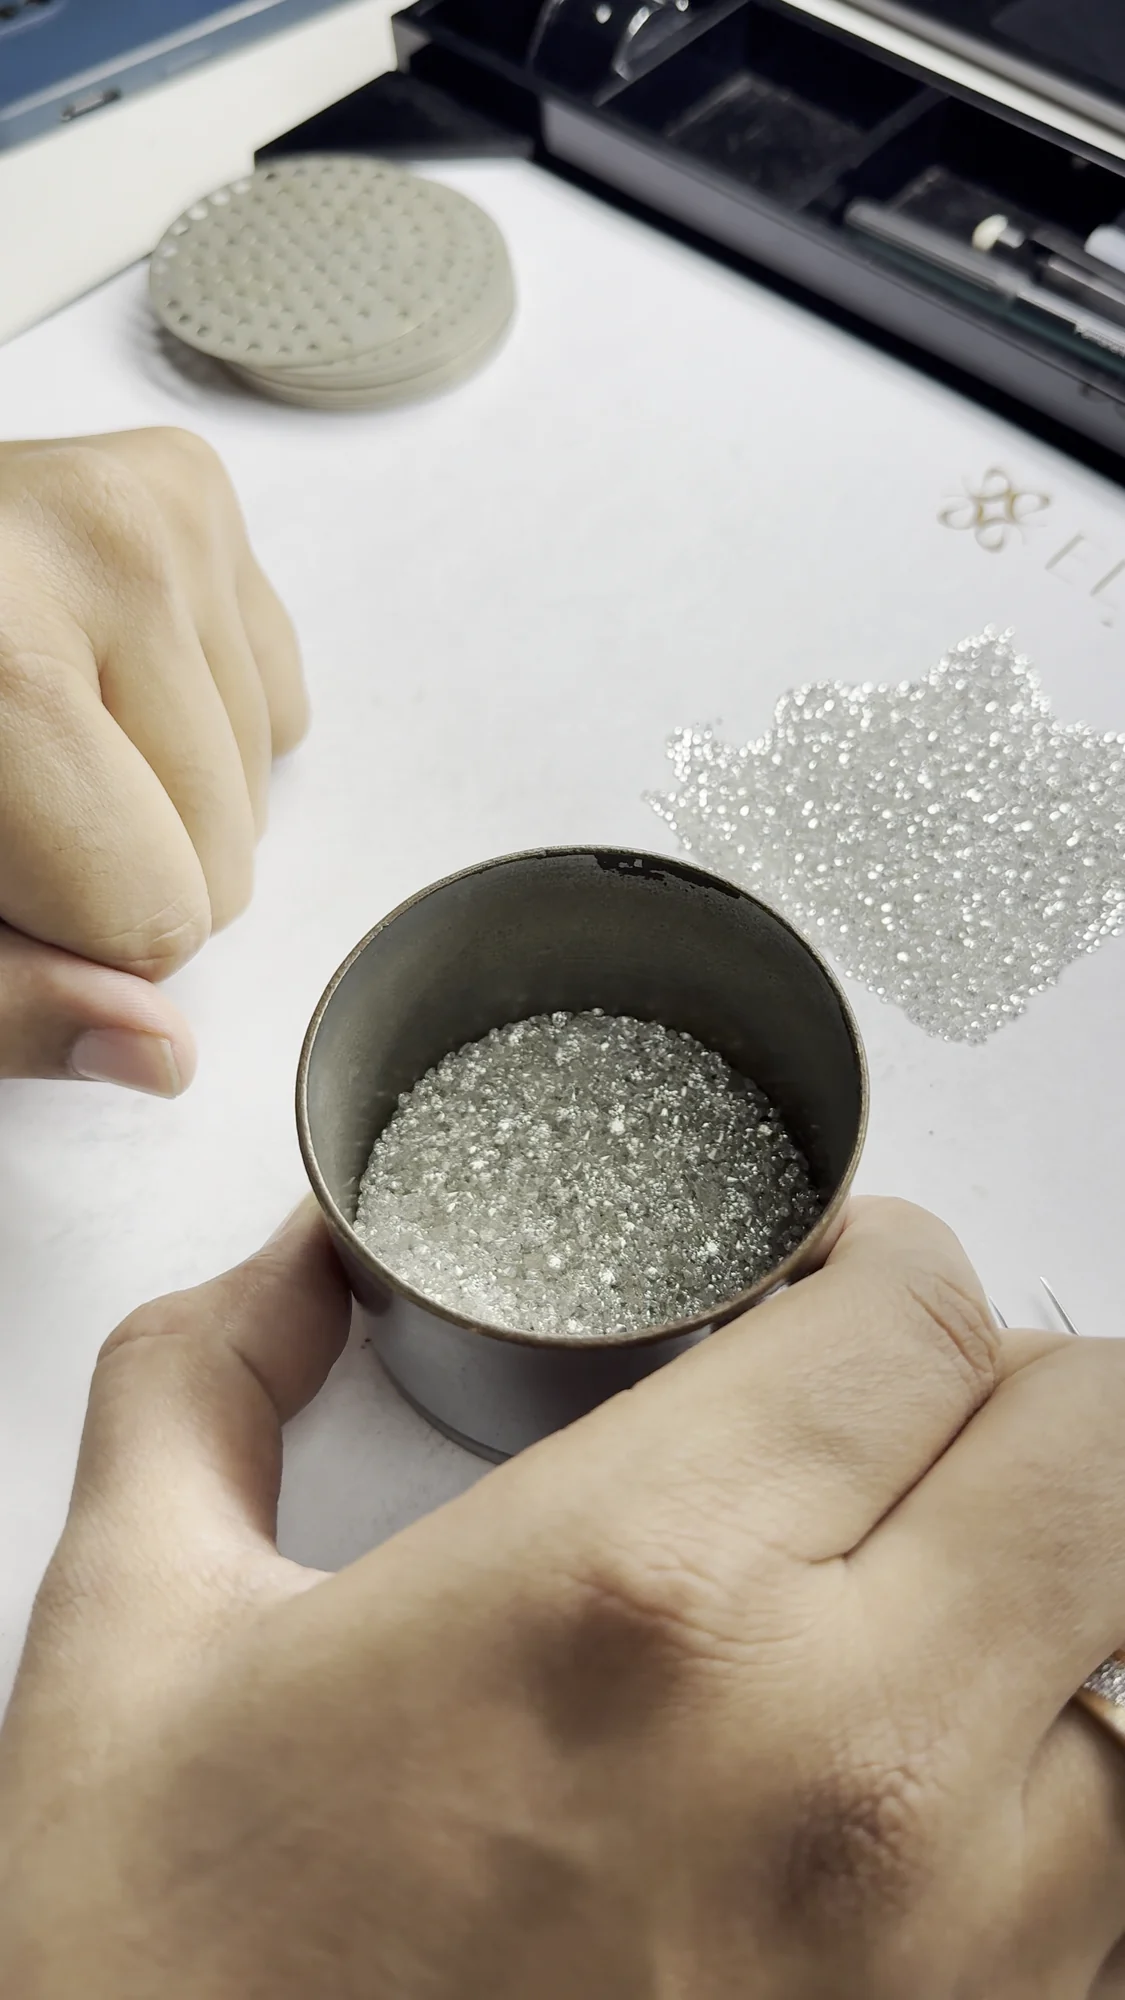
Rough diamond prices vary significantly by quality. Near-gem rough from Botswana (De Beers Sightholders) trades at $100–$500/ct for commercial mixes; fine run-of-mine material in the 0.5–2ct range trades at $250–$800/ct. Exceptional rough — D-colour, octahedral crystals above 2ct — can reach $1,500–$3,000/ct and above.
Get the Report
Every Month.
This market intelligence briefing is emailed to verified wholesale buyers monthly. To receive it, submit a trade inquiry — we include it in all active B2B relationships.
Anand Exports has been our primary rough supplier for over twelve years. Their consistency in parcel quality and documentation is unmatched in the market.